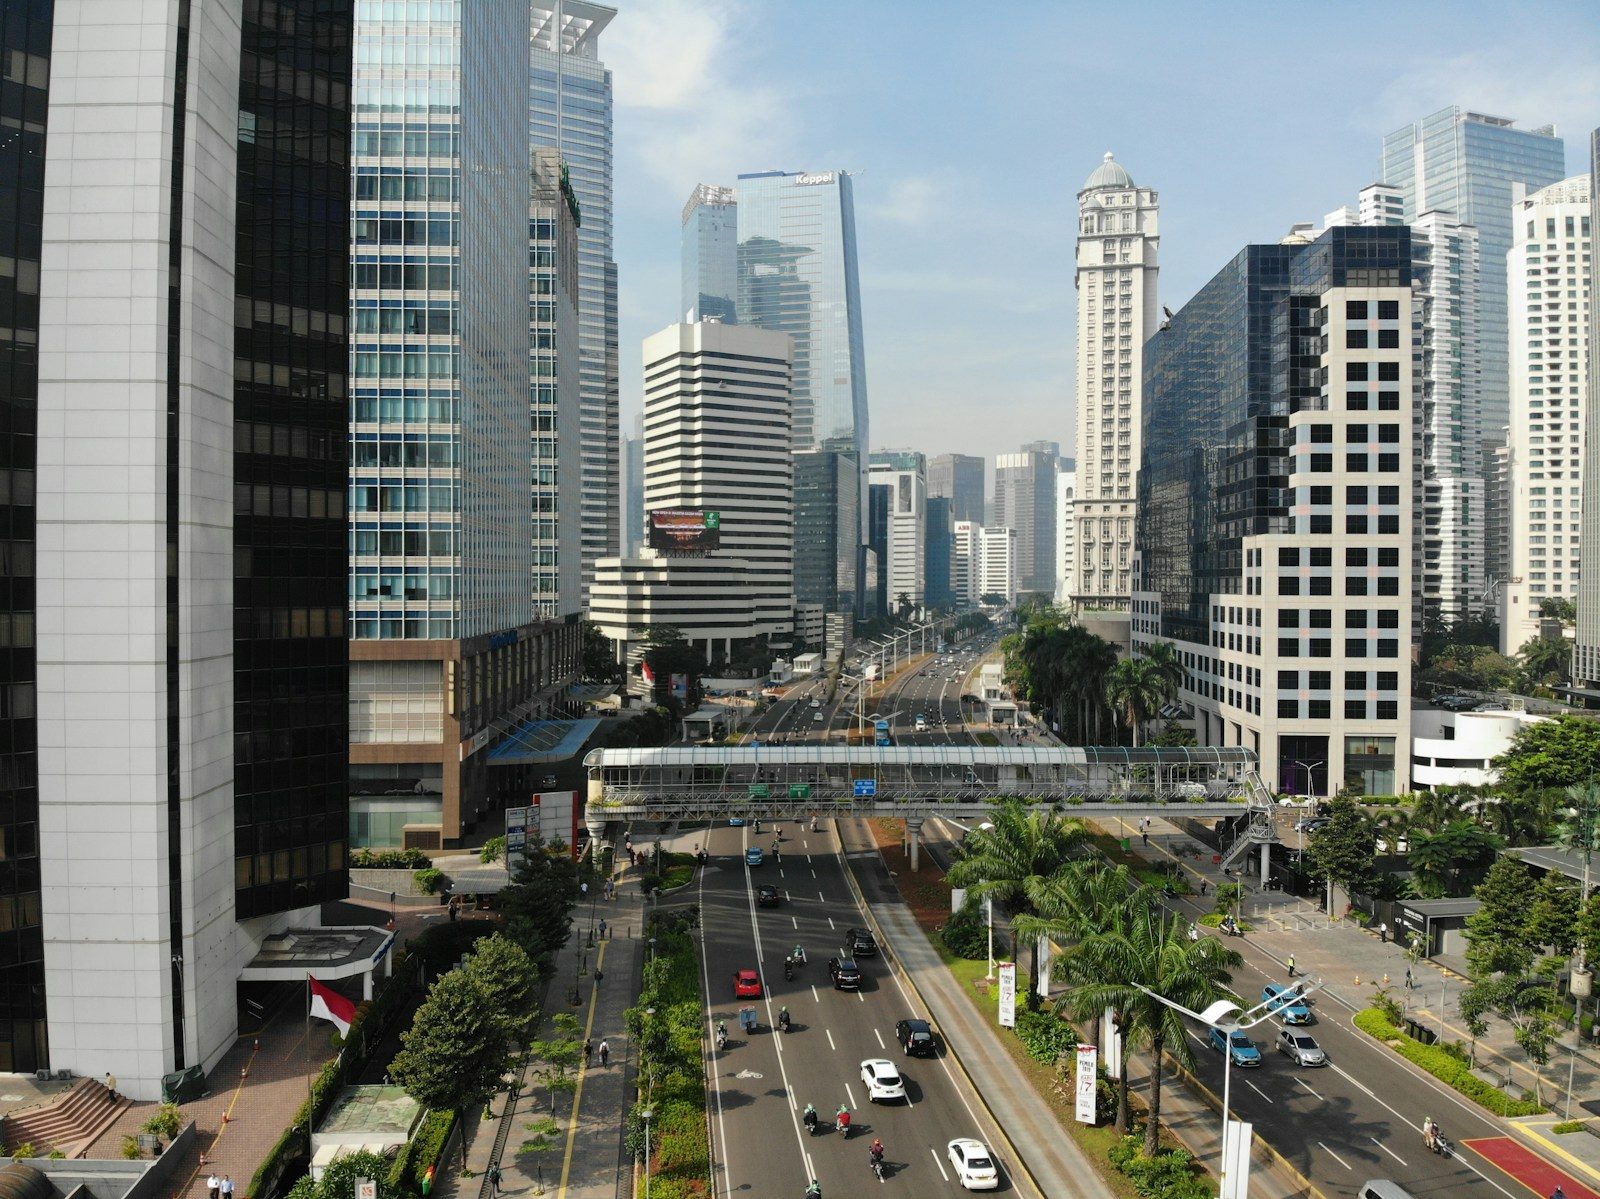
Indonesia has solidified its position as a powerhouse in the Southeast Asian economy. Driven by a rapidly expanding middle class and strong market fundamentals, Indonesia’s GDP is projected to grow by 5.2 percent through 2026 and 2027 according to the Asian Development Bank, making it a prime destination for foreign corporate investment. In the first half of 2026 alone, the country achieved an impressive investment realization of over 56 billion USD, with foreign direct investment accounting for more than half of this total. However, expanding into this booming emerging market requires more than just capital. It demands a deep understanding of structural, legal, and tax-related hurdles unique to the local economy.
Establishing a Strong Compliance Foundation
Before diving into specific Indonesian regulations, decision-makers must recognize that localized governance and statutory roles are non-negotiable. Building a solid strategy on how to maintain corporate compliance when expanding your business overseas is crucial to avoid steep financial penalties. Entering heavily regulated markets in Southeast Asia demands a proactive approach to risk management, which often involves budgeting for unexpected regulatory hurdles and appointing resident officials to oversee local operations.
Many foreign entities struggle to bridge the gap between their home country’s regulations and Indonesia’s distinct legal landscape. When evaluating whether to handle operations internally or outsource them, executives often ask themselves, Who provides professional corporate services in Indonesia? By partnering with specialized local firms, foreign companies can seamlessly manage company formation, tax compliance, and payroll outsourcing while focusing entirely on their core business growth strategies.
Corporate Structuring and Capital Requirements
When entering the Indonesian market, the most common vehicle for foreign investors is the foreign-owned limited liability company, legally known as a PT PMA. Establishing a PT PMA allows foreign business owners to maintain full or partial control over their corporate operations, depending on the specific sector’s foreign ownership limits dictated by the Positive Investment List. Recent regulatory shifts under the Ministry of Investment have modified the financial barriers to entry, making it more accessible while maintaining strict operational standards. Key financial requirements for structuring this entity include:
- Minimum paid-up capital: The required paid-up capital for establishing a PT PMA has been reduced by 75 percent to 2.5 billion Indonesian Rupiah (roughly 150,000 USD).
- Total investment plan: Despite the lowered paid-up capital threshold, companies must still commit to an investment plan exceeding 10 billion Rupiah per 5-digit business classification code. This figure generally excludes the value of land and buildings.
- Capital retention rules: To prevent the creation of shell companies, regulators strictly mandate that this paid-up capital must remain in the corporate bank account for at least 12 months, unless it is actively utilized for verified business operations.
Navigating Regulatory Licensing and Digital Platforms
Licensing in Indonesia has undergone significant modernization in recent years. The Online Single Submission Risk-Based Approach assigns business activities into four distinct risk categories. These categories (low, medium-low, medium-high, and high) dictate the exact operating permits and standard certificates a company must secure before officially launching its operations.
As of 2026, this digital licensing system is governed by Government Regulation No. 28 of 2025. This critical update was designed to centralize licensing authority and overcome previous issues of regional regulatory fragmentation. By digitizing the application process, the Indonesian government aims to provide foreign investors with a more predictable and streamlined path to market entry.
Taxation Framework and Recent Updates
Financial compliance remains one of the most critical ongoing priorities for expanding entities. The year 2026 marks the first major corporate filing cycle that mandates the use of Coretax, Indonesia’s modernized central digital platform for tax registration, calculation, and payment. Adapting to this new system requires proactive financial planning and dedicated administrative resources. Foreign businesses must ensure their internal accounting teams are fully trained on the platform’s updated interface and reporting formats.
Indonesia’s standard Corporate Income Tax rate is currently a flat 22 percent applied to net taxable income, though eligible publicly listed companies can qualify for a reduced rate of 19 percent. Additionally, newly introduced regulations have eliminated the simplified 0.5 percent final income tax regime for limited liability companies, forcing these entities to transition to the standard corporate tax calculation system. With the statutory Value Added Tax rate recently increasing to 12 percent, accurate transaction tax calculation is more important than ever to ensure full compliance.
Expanding a business into Indonesia offers immense potential for growth, backed by robust macroeconomic indicators and sustained foreign direct investment inflows. However, success in this dynamic market hinges on strict adherence to corporate structuring rules, modernized digital licensing, and updated taxation frameworks. By understanding these essential legal and financial considerations, foreign investors can mitigate risks and establish a thriving, compliant enterprise in one of Southeast Asia’s most promising economies.